Mat Simmons, founder and managing principal — Wexford, Pennsylvania
Tell us a little about what you're looking for and we'll take it from there. Accredited investors only — $100,000 minimum.
There are three usual paths. Each one breaks in a predictable place.
Where it breaks: the word "passive"
You've bought a job with leverage attached. Turnover, capex, insurance renewals, tax reassessments and one bad tenant can erase a year of cash flow — and your entire position sits in one submarket you happen to live near.
Where it breaks: correlation
Liquid and genuinely hands-off, but priced by the same equity market you were trying to diversify away from. When your stock portfolio draws down, so does this. You own a ticker, not an asset.
Where it breaks: concentration
Real assets and real sponsors, but you're underwriting one building, one operator and one business plan at a time. Get the deal wrong and there's nothing else in the position to carry it.
Not a strategy deck. These are current positions, with the terms that make them work.
Access covers the fund structure, the five asset types and the current positions.
Request access or book a callThis is a real structural gap, not a marketing angle.
Institutional capital has a minimum efficient check size. A billion-dollar allocator can't deploy $3M at a time — the diligence, legal and asset management cost per dollar doesn't work. So the sub-$5M band gets left to local operators who are usually undercapitalized, slow to close, and financing-contingent.
We sit in that band deliberately: below where institutions can operate efficiently, above where individual buyers can compete on speed and certainty. It's where a seller will still trade price for a clean close, and where relationships and local knowledge are worth actual basis points.
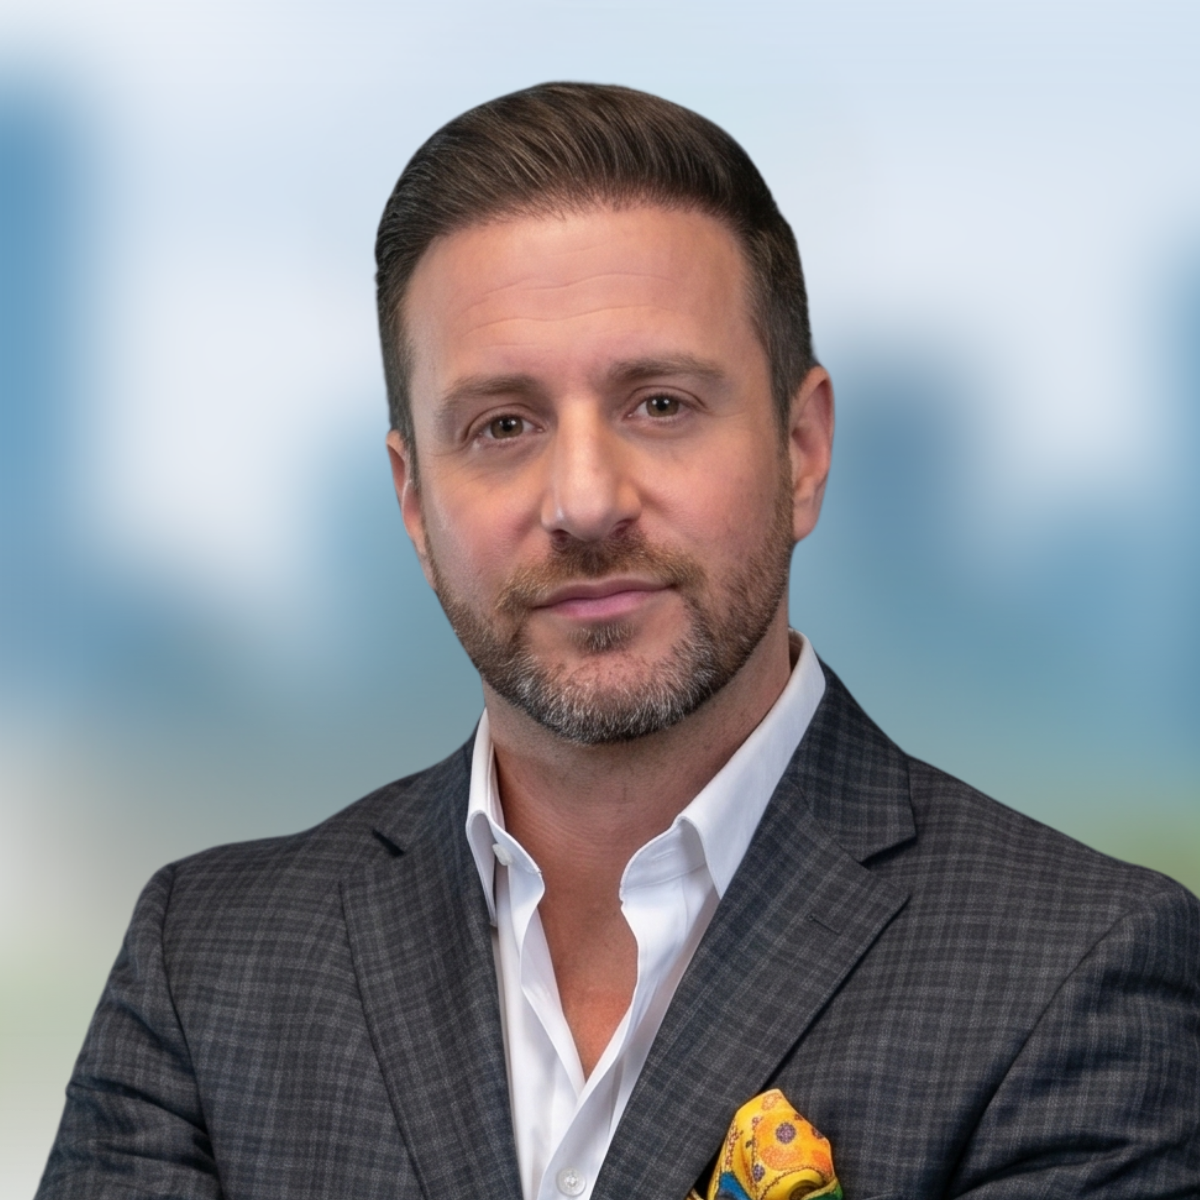
Mathew Simmons is founder and managing principal of SIMM Capital. He has been raising and deploying capital since 2006 and has spent roughly twenty years operating businesses across real estate, manufacturing and retail — including exits, and including one that went through bankruptcy.
That last part matters more than the wins. Most sponsors will show you a track record with the failures edited out. Having taken a business all the way down teaches you exactly which assumptions break first, and it is the reason this fund holds fixed-rate debt, sits above equity where it can, and is built to be diversified rather than concentrated in whatever is working this year.
He leads every term negotiation and signs off on every subscription personally. He is also the author of Become Scaleable.
Cash, people, inventory, customers. Everything else in a business is commentary on those four.
Questions about any of that are better answered directly than in a brochure.
Book a call with our team or read the package firstNo pressure, no calendar traps. You can stop at any step.
Our investor relations team reaches out to understand what you're looking for. Usually within one business day.
A direct call with our investor relations team, or with Mat. The point is to answer your questions and to determine whether this is a fit — in both directions.
Rule 506(c) requires that we take reasonable steps to verify accredited status before accepting capital. Once that's complete you receive the private placement memorandum and subscription documents to review — ideally with your own counsel and tax advisor.
If you decide to proceed, you execute the subscription documents and fund. Reporting and distributions follow the schedule set out in the fund documents.
Under SEC rules, an accredited investor generally has income above $200,000 individually or $300,000 jointly with a spouse in each of the two most recent years, or a net worth above $1 million excluding a primary residence. Certain professional certifications and licenses also qualify. This fund is offered under Rule 506(c), which permits us to advertise publicly but requires us to take reasonable steps to verify that every investor is accredited before accepting capital. That verification is a documented process, not a checkbox.
$100,000. Terms and any exceptions are set out in the fund documents.
It isn't. This is a private fund holding real property and private debt positions, and you should plan on your capital being committed for the term described in the fund documents. Any redemption or transfer provisions are spelled out there. If you may need the principal back on short notice, this is the wrong vehicle — and we'd rather tell you that now than at closing.
Limited partners receive a 10% preferred return, paid monthly, ahead of the sponsor in the order of payment. That is a targeted rate rather than a guaranteed one — no private real estate fund can guarantee a future distribution. Actual distributions depend on the performance of the underlying assets and are made to the extent available under the fund documents, and the usual real estate risks apply: vacancy, rate movements, property tax and insurance increases, construction delays and market conditions.
Yes. Our annual investor updates set out the pressures on the portfolio directly rather than in general terms — repositioning, rising property taxes and insurance costs, elevated interest rates, and housing authority budget reductions have all been named in writing to investors. We'd rather send an uncomfortable letter than a vague one. Ask us for the most recent one; how a sponsor writes about a hard year tells you more than any track record slide.
Investors receive a Schedule K-1. Real estate funds often generate depreciation that can shelter a portion of distributions, and dispositions may produce long-term capital gain treatment, but the outcome depends entirely on your own situation, entity structure and state. Nothing here is tax advice — review the fund documents with your CPA before subscribing.
A syndication is normally a single asset with a single business plan; if it underperforms, that's your whole position. This is a fund holding positions across five asset types — single-family workforce housing, stabilized multifamily, NNN commercial retail, development and new construction, and credit and debt — including positions senior to equity, which get paid before sponsors do. You're delegating allocation across a portfolio rather than underwriting one building at a time.
Yes. He leads every term negotiation and signs every subscription. If you're seriously evaluating an allocation, you'll talk to him before you commit capital.
Request access and we'll be in touch. If it's a fit, we'll go further. If it isn't, you'll know quickly and nobody will chase you.
SIMM Capital · Pittsburgh, Pennsylvania · Investment opportunities offered under Rule 506(c) of Regulation D to verified accredited investors only.
Takes about a minute. Accredited investors only.